- Key Takeaways
- What an Expense Ratio Actually Costs You
- The February 2026 Vanguard Fee Cut Nobody Covered
- Where the Toll Hides: Three Costs No Fact Sheet Shows
- The Advisory Fee Layer and the Fee Waiver Trapdoor
- The Hurdle Rate and What SPIVA Says About Clearing It
- When a Fee Is Genuinely Earned
- Watch the Full Breakdown
- Running the Numbers on Your Own Portfolio
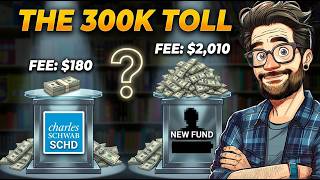
A new dividend ETF began trading on September 2, 2026. Its own prospectus admits it has no performance history and that portfolio turnover data isn't yet available, since the fund has never traded. On a $300,000 position, that fund would charge $2,010 in its first year. SCHD, the largest dividend ETF in America, charges just $180 a year on the same balance. The $1,830 difference is what's worth examining closely, because it's arguably the only number in a portfolio that is knowable in advance, guaranteed, and collected every single day the market is open.
Key Takeaways
- A new active dividend ETF charges 0.67% (after a fee waiver) versus SCHD's 0.06% expense ratio — a $1,830 annual gap on $300,000
- Vanguard cut fees on 53 funds and 84 share classes in February 2026, dropping VIG and VYM to just 0.04%
- Hidden costs — portfolio turnover, bid-ask spreads, and capital gains distributions — never appear on a fund's fact sheet
- A 1% advisory fee stacked on a $500,000 portfolio can cost more than $500,000 over twenty years
- SPIVA's 2025 scorecard found 93% of active large-cap funds underperformed their benchmark over 20 years
- The "hurdle rate" — the fee gap between two funds — tells you exactly how much outperformance an expensive fund must deliver just to break even
What an Expense Ratio Actually Costs You
An expense ratio never shows up as a line-item deduction on a brokerage statement. It's deducted from a fund's net asset value every single day before the price investors see is calculated, which is exactly why so many investors never notice what they're paying. On $300,000, a fund charging 0.06% costs $180 a year. A fund charging 0.67% costs $2,010 a year. Same balance, same market conditions, dramatically different cost.
SCHD tracks the Dow Jones U.S. Dividend 100 Index, holding roughly 100 established dividend-paying companies screened for return on equity, cash-flow-to-debt ratios, and consistent payout history. The fund yields just over 3%, manages an estimated $112–113 billion in assets, and has traded since 2011, giving it a genuine multi-year track record. For 0.06% a year, investors get a mechanically run, rules-based portfolio with minimal trading and minimal cost.
That said, cheap doesn't mean flawless. SCHD is value-tilted, meaning it tends to lag in growth-led markets, and its March 2026 reconstitution cut energy exposure by roughly eight percentage points, altering the fund's character for anyone who owned it specifically for energy income. Cost and quality are separate questions — a low expense ratio simply means the price of finding out whether a fund performs well is small.
The February 2026 Vanguard Fee Cut Nobody Covered
On February 1, 2026, Vanguard quietly cut fees across 84 share classes spanning 53 funds — an average reduction of about 27%, expected to save investors roughly $250 million this year. VIG (Vanguard Dividend Appreciation), which tracks companies with at least ten consecutive years of dividend increases, dropped from 0.05% to 0.04%. VYM (Vanguard High Dividend Yield) fell from 0.06% to 0.04%. On $300,000, that's $120 a year for either fund.
Compare that timeline to the same industry's other headline: seven months after Vanguard's fee cut, a brand-new active fund launched at 0.67%. Only one of those stories made the news, even though both happened in the same market within the same year. Investors comparing dividend ETFs for retirement or income should note where fees on established index products are heading — and where new product launches are pricing themselves instead.
The Middle of the Range
Not every fund sits at either extreme. DGRO (iShares Core Dividend Growth) charges 0.08% and yields under 2%. DGRW (WisdomTree U.S. Quality Dividend Growth) charges 0.28% and pays monthly. On $300,000, DGRW costs $840 in year one versus $180 for a 0.06% fund — a 22-basis-point gap that compounds to roughly $60,371 in lost ending balance over 20 years at an assumed 8.5% gross annual return. That doesn't make DGRW a bad fund; monthly income has real value for someone living off a portfolio. But investors should know what that convenience costs before deciding it's worth it. For a deeper comparison of these exact funds working together, see the 4-ETF Dividend Ladder breakdown of VIG, DGRO, SCHD and DIVO.
Where the Toll Hides: Three Costs No Fact Sheet Shows
Every fee discussed above is printed on a fact sheet. The next three are not disclosed anywhere directly.
Portfolio Turnover
Every time a fund buys or sells a holding, it pays commissions and absorbs bid-ask spread costs — none of which appear in the expense ratio. Turnover varies enormously across dividend funds: VOO turns over about 2% of its portfolio annually, VYM about 11%, DGRO about 25%, DGRW about 41%, and RDVY (a rising dividend achievers fund) about 69%. Research into trading costs for large, liquid U.S. stocks generally finds round-trip costs ranging from a few basis points to a couple of tenths of a percent, depending on size and urgency. Two funds with identical published expense ratios but different turnover rates are not costing investors the same amount — the published number is incomplete. The new fund discussed here can't disclose turnover because it has never traded, but its own prospectus warns that frequent trading strategies may cause it to underperform less active peers.
Bid-Ask Spreads on New Funds
Every ETF trade crosses a spread between the buy and sell price. On heavily traded funds, that gap rounds to nothing noticeable. On a brand-new fund with limited assets, the prospectus for the new fund discussed here explicitly warns that with a limited number of authorized participants, bid-ask spreads may widen, and it flags market maker risk separately, since it may rely on a small number of third-party market makers.
Tax Drag in Taxable Accounts
When a fund sells a holding at a profit, it must distribute that capital gain to shareholders — generating a tax bill for a transaction the investor never made. Higher turnover means more of these events. This is one structural reason mechanical, low-turnover index dividend funds have historically been more tax-efficient in taxable brokerage accounts than actively managed, higher-turnover alternatives.
The Advisory Fee Layer and the Fee Waiver Trapdoor
An investor with $500,000 paying a typical 1% advisory fee on top of funds averaging 0.30% carries an all-in cost of 1.3%, or $6,500 in year one. The same $500,000 in a low-cost index portfolio at 0.10% all-in costs $500 in year one. Over 20 years at an assumed constant return, the stacked-fee portfolio grows to roughly $2,008,472, while the low-cost portfolio grows to roughly $2,509,318 — a gap of $500,846, which is more than the original starting balance.
The new fund highlighted at the top of this article charges 0.71% gross, reduced to 0.67% only through a contractual fee waiver. That waiver expires no later than August 31, 2027, and can be terminated earlier by the board at any time, or by the fund's adviser with just 30 days' notice. If the waiver lapses, the fee doesn't hold steady — it rises to the full 0.71%.
Subtract the cheap fund's fee from the expensive fund's fee, and that's the amount of extra return the expensive fund must produce every single year, forever, just to tie.
The Hurdle Rate and What SPIVA Says About Clearing It
The 61-basis-point gap between the new fund (0.67%) and SCHD (0.06%) is the hurdle: the expensive fund must beat the cheap one by 0.61% annually, every year, indefinitely, just to match it. At an assumed 8.5% gross annual return, SCHD nets 8.44% and grows $300,000 to roughly $1,516,741 over 20 years. The 0.67% fund nets 7.83% and grows the same $300,000 to roughly $1,354,919. The gap, $161,822, translates at a 3% yield to about $4,855 of annual income lost permanently — roughly 18 years of the portfolio's own income, gone to a fee rather than a market downturn.
The S&P Dow Jones Indices SPIVA U.S. scorecard, which has tracked active fund performance against benchmarks for 25 years, found that in its year-end 2025 report (published March 2026), 79% of active large-cap U.S. equity funds underperformed the S&P 500 — the fourth-worst showing in the scorecard's history. Over three years, 67% underperformed; over five years, 89%; over 20 years, 93%. Active large-cap funds average roughly 0.64% in fees against roughly 0.05% for index funds — a gap that closely mirrors the hurdle calculated above.
When a Fee Is Genuinely Earned
Not every active fee fails the test. CGDV (Capital Group Dividend Value) charges 0.33%, more than five times a cheap index fund, but according to Morningstar's April 2026 analysis, it returned about 16% annualized from its February 2022 launch through March 2026, versus roughly 12.3% annualized for its benchmark — a gap comfortably above its own hurdle. A longer-view composite tracing the same strategy back to 2007 through a mutual fund wrapper shows about 10.6% annualized versus 8% for a value index, though it essentially matched the broad market over that longer stretch. At 0.33%, CGDV also sits in the cheapest quintile of its active category, where the median fee runs closer to 0.75%. It's a genuine example of active management clearing its hurdle so far — while still needing to keep proving it every year.
Watch the Full Breakdown
This article summarizes the arithmetic, but the video walks through all twelve fee decisions step by step, including the full 20-year compounding math on a $300,000 dividend portfolio and a side-by-side look at the new fund's actual prospectus language. Watching it is the fastest way to see exactly how the $1,830 toll is calculated and how to apply the same hurdle test to any fund sitting in your own account.
Running the Numbers on Your Own Portfolio
The practical exercise takes about five minutes: list the expense ratio of every fund owned, multiply each by the dollar amount held, and add them up to find total annual fee drag. For any fund charging more than roughly 0.20%, apply the hurdle by subtracting the cheapest comparable alternative's fee and asking whether that fund has actually beaten its benchmark by that much, annually, over a meaningful period. If the fund in question is held in a taxable account with a large embedded gain, selling purely because it's expensive can trigger a tax bill larger than several years of the fee being avoided — in that case, redirecting new contributions to the cheaper fund is usually the better move. For investors building a broader low-cost dividend allocation, the SCHD and SCHG 70/30 core-satellite strategy is one framework worth reviewing alongside this fee analysis.
Every figure above is dated to early September 2026 and drawn from fund fact sheets, the new fund's prospectus, Vanguard's February 2026 announcement, and the SPIVA U.S. scorecard. The 8.5% long-run return used in the compounding examples is a stated assumption, not a forecast, and none of this constitutes financial or tax advice.